

GE Vernova T&D India has attracted positive ratings from Nomura, JPMorgan and Citi after strong Q2 FY27 earnings. A ₹21,443 crore order backlog, rising profitability and power grid investments support the growth outlook, although Jefferies remains cautious.
GE Vernova T&D India Ltd has emerged as a closely watched power infrastructure stock after several global brokerages reviewed the company’s September 2026 quarter earnings and growth prospects.
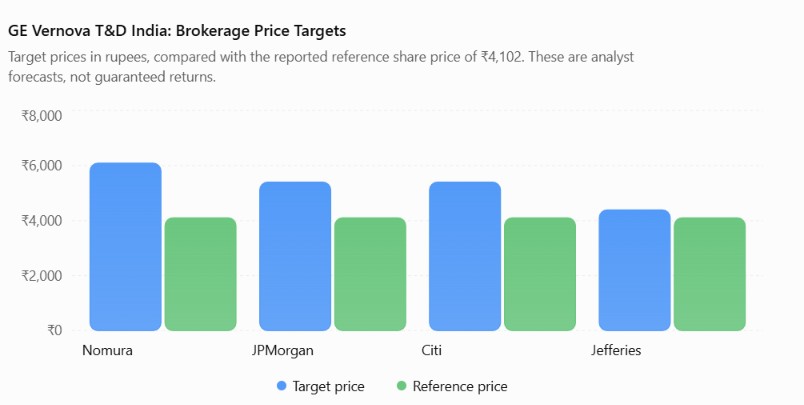
Nomura has maintained a Buy rating with a target price of ₹6,090, suggesting potential upside of approximately 48.5% from the reported market price of ₹4,102 per share.
JPMorgan and Citi have also retained positive recommendations, each setting a target price of ₹5,400. Jefferies, however, has maintained a Hold rating with a more conservative target of ₹4,390.
See more of our coverage in your search results.
Add INDYASTORY on GoogleThe different forecasts highlight how brokerages are assessing the company’s earnings growth, order execution, margins and valuation.
According to the supplied market data, GE Vernova T&D India shares were trading at approximately ₹4,102, down 1.75% from the previous close. The company had a reported market capitalisation of around ₹1.05 lakh crore and a one-year share-price return of approximately 28.8%.
The bullish outlook follows a quarter in which revenue increased 32% year-on-year and net profit rose 44%, supported by project execution and stronger operating profitability.
However, analysts continue to monitor the timing of major transmission projects and the sustainability of export demand.
GE Vernova T&D India Share Price Targets: What Are Brokerages Predicting?
Four major international brokerages have provided different assessments of GE Vernova T&D India’s potential performance.
See more of our coverage in your search results.
Add INDYASTORY on GoogleNomura has the highest stated target among the four at ₹6,090, while JPMorgan and Citi share a ₹5,400 target.
Jefferies has adopted a relatively cautious position with its ₹4,390 objective.
Brokerage Ratings and Target Prices
| Brokerage | Rating | Target price | Implied upside |
|---|---|---|---|
| Nomura | Buy | ₹6,090 | 48.5% |
| JPMorgan | Overweight | ₹5,400 | 31.6% |
| Citi | Buy | ₹5,400 | 31.6% |
| Jefferies | Hold | ₹4,390 | 7.0% |
Upside percentages are calculated against the reported reference price of ₹4,102. They are not guaranteed investment returns. Original brokerage research dates and investment horizons require verification.
See more of our coverage in your search results.
Add INDYASTORY on GoogleThe difference between the highest and lowest price targets is ₹1,700 per share.
This wide range suggests that the market’s assessment of the company’s future earnings and valuation remains sensitive to execution assumptions.
While the majority of the cited brokerages maintain positive ratings, their forecasts should be considered independently rather than interpreted as a consensus guarantee.
Why Nomura Sees Nearly 48% Upside in GE Vernova T&D India
Nomura’s bullish recommendation is supported by strong quarterly operating performance, improving international order inflows and expectations of sustained demand for transmission infrastructure.
The brokerage has maintained its Buy rating and set a ₹6,090 target price.
Q2 EBITDA Beats Expectations
GE Vernova T&D India reported EBITDA of approximately ₹550 crore for the September 2026 quarter, compared with ₹396 crore in the corresponding period of the previous year.
This represents growth of approximately 39% year-on-year.
According to Nomura’s assessment cited in the supplied report, the quarterly EBITDA exceeded its estimate by around 13%.
The earnings beat suggests that operating performance was stronger than the brokerage had anticipated.
For capital equipment and infrastructure businesses, margin improvements can have a substantial impact on earnings when revenue and project execution volumes increase.
However, investors should assess whether the stronger performance reflects sustainable operating efficiencies or benefits from a favourable project mix.
Export Orders Support Growth Expectations
Nomura also highlighted improving international demand.
The company’s export order intake during the first half of FY27 was reportedly nearly equal to the total export orders received throughout FY26.
That development indicates stronger export momentum during the reported period.
International orders can broaden the company’s revenue opportunities beyond India’s transmission and distribution market.
Nevertheless, export revenue growth depends on project execution timelines, customer requirements, foreign exchange movements and international trade conditions.
Strong order intake does not necessarily translate into revenue immediately.
Nomura Expects Strong Earnings Growth Through FY29
Management has reportedly outlined an ambition to achieve approximately 30% compound annual revenue growth over the next three to four years.
Nomura also expects earnings to grow at around 30% annually between FY26 and FY29.
The brokerage has increased its FY27–FY29 earnings-per-share estimates by approximately 1–4%, reflecting its more positive outlook following quarterly results.
These expectations are supported by opportunities in grid expansion, electricity transmission infrastructure and digitalisation.
However, the forecasts depend on the company’s ability to secure and execute projects while maintaining profitable margins.
JPMorgan Maintains Overweight Rating With ₹5,400 Target
JPMorgan has retained an Overweight rating on GE Vernova T&D India, with a target price of ₹5,400.
This indicates potential appreciation of approximately 31.6% from the ₹4,102 reference price.
The brokerage’s assessment focuses on improving profit margins, a strong order pipeline and opportunities arising from large transmission projects.
EBITDA Margin Expands to 27.1%
GE Vernova T&D India’s EBITDA margin improved to approximately 27.1% during Q2 FY27.
The reported improvement was 135 basis points year-on-year and 203 basis points sequentially.
Higher margins indicate that the company generated more operating profit from each rupee of revenue during the period.
JPMorgan views the improvement in profitability alongside stronger order inflows as an important positive development.
However, project-based businesses can experience changes in margins depending on the contract mix, execution stage, input costs and revenue recognition.
The company’s ability to maintain strong margins across multiple quarters will therefore be an important indicator of earnings quality.
US Data Centre Order Could Create Additional Opportunity
Another development highlighted by JPMorgan involves a potential US data centre-related transaction.
According to the supplied brokerage commentary, the company has an active approval for a related-party transaction of approximately $151 million associated with a US data centre order.
Negotiations were reportedly continuing, with a potential conclusion expected during the second half of the relevant period.
The opportunity is noteworthy because data centres require reliable electrical infrastructure, including transformers, switchgear and power distribution systems.
However, an approved related-party transaction limit should not automatically be treated as a confirmed order or recognised revenue.
Investors should monitor formal company disclosures to establish whether a contract is finalised and on what commercial terms.
Barmer HVDC Project Could Support Future Order Growth
JPMorgan also expects a major order opportunity connected with the Barmer high-voltage direct current (HVDC) transmission project.
The brokerage commentary refers to a potential project order of approximately $1.5 billion that could be booked in Q3 FY27.
However, meaningful execution is reportedly expected to begin primarily in FY29.
This distinction is important.
A large order may increase a company’s reported backlog long before the related revenue and profit are recognised.
Project timing, contractual scope, consortium arrangements and regulatory milestones can affect the eventual financial contribution.
Management has also reportedly identified two or three potential new HVDC projects in India that could be finalised during calendar year 2027.
These opportunities could strengthen the long-term pipeline, but they remain prospective until contracts are formally awarded.
Citi Maintains Buy Rating on GE Vernova T&D India
Citi has maintained its Buy rating on the company, with a ₹5,400 target price.
The brokerage’s positive view follows strong quarterly order inflows, better-than-expected margins and favourable execution conditions.
New Orders Rise 52% to ₹2,438 Crore
GE Vernova T&D India’s reported order inflows increased 52% year-on-year to ₹2,438 crore during Q2 FY27.
Citi highlighted that the order intake exceeded its expectations.
Demand from domestic customers and international markets reportedly supported the increase.
Strong inflows are significant because they help replenish the order backlog as the company completes existing projects.
However, order intake can vary considerably between quarters in a project-driven business.
Investors should therefore evaluate order trends over a longer period rather than relying exclusively on one strong quarter.
Revenue and Profitability Beat Expectations
Quarterly revenue increased 32% year-on-year to ₹2,027 crore, broadly in line with Citi’s expectations.
EBITDA margin of approximately 27.1%, however, exceeded the brokerage’s estimate by around 200 basis points.
The better-than-expected margin was attributed to favourable project execution.
Citi also highlighted management’s positive view of second-half FY27 order activity, particularly opportunities under the tariff-based competitive bidding (TBCB) framework.
The company reportedly maintained its FY27 EBITDA margin guidance at approximately 25%.
That guidance is lower than the reported Q2 margin of 27.1%, indicating that management is not necessarily assuming the exceptionally strong quarterly margin will persist throughout the year.
Citi continues to monitor domestic order growth and export momentum, including potential uncertainty associated with India-US trade conditions.
Why Jefferies Is More Cautious on GE Vernova T&D India
Unlike Nomura, JPMorgan and Citi, Jefferies has maintained a Hold rating.
Its target price of ₹4,390 represents approximately 7% potential upside from the reported reference price.
The more conservative assessment reflects concerns over the visibility of export growth and delays affecting certain large orders associated with the company’s parent group.
Better Quarterly Results, but Export Risks Remain
Jefferies acknowledged that the company’s Q2 FY27 EBITDA exceeded its estimate by approximately 3%.
The brokerage also recognised the improvement in EBITDA margin to around 27%, supported by stronger gross margins.
Following the results, Jefferies reportedly increased its FY27–FY30 earnings estimates by approximately 0–2%.
However, the revisions were modest compared with the optimism reflected in the highest brokerage target.
Jefferies believes India’s domestic transmission market offers meaningful growth opportunities.
Its main reservation concerns the timing and consistency of large export orders, particularly those linked to group-related business.
Delays in such projects may create uncertainty around revenue growth and limit opportunities for further margin improvement.
The contrasting brokerage opinions highlight why investors should examine both the optimistic and cautious scenarios before assessing valuation.
GE Vernova T&D India Q2 FY27 Results: Revenue, EBITDA and Profit Rise
GE Vernova T&D India reported broad-based financial growth during the quarter ended September 30, 2026, according to the supplied financial information.
Revenue increased to approximately ₹2,027 crore from ₹1,538 crore a year earlier.
EBITDA rose to ₹550 crore from ₹396 crore, while net profit increased to ₹431 crore from ₹299 crore.
Earnings per share also improved, rising to ₹16.85 from ₹11.70.
Q2 FY27 Financial Performance
| Financial metric | Q2 FY26 | Q2 FY27 | Reported YoY growth |
|---|---|---|---|
| Revenue | ₹1,538 crore | ₹2,027 crore | 32% |
| EBITDA | ₹396 crore | ₹550 crore | 39% |
| Net profit | ₹299 crore | ₹431 crore | 44% |
| EPS | ₹11.70 | ₹16.85 | 44% |
| EBITDA margin | — | 27.1% | Up 135 bps |
Source: Financial figures provided in the underlying report. Verify against the company’s official September 2026 quarterly results.
The results show that EBITDA and net profit expanded faster than revenue.
This indicates improved profitability during the reported quarter.
However, one quarter of strong results does not establish a permanent margin trend.
Investors should monitor how the company performs as its project mix changes and new large contracts enter the execution stage.
GE Vernova T&D India’s Order Book Stands at ₹21,443 Crore
A key factor supporting the company’s growth outlook is its substantial order backlog.
According to the supplied information, GE Vernova T&D India reported an outstanding order book of approximately ₹21,443 crore as of September 30, 2026.
The backlog was around ₹21,460 crore at the end of March 2026 and ₹20,930 crore at the end of June 2026.
Order Backlog Trend
| Reporting period | Order backlog |
|---|---|
| March 2026 | ₹21,460 crore |
| June 2026 | ₹20,930 crore |
| September 2026 | ₹21,443 crore |
The order book increased approximately 2.5% from June to September, although it remained broadly unchanged compared with March.
This suggests that new orders helped replenish the pipeline during the September quarter.
For a company operating in transmission equipment and project execution, maintaining a sizeable backlog is important because revenue is recognised as contracts progress through execution.
However, an order backlog is not equivalent to cash in hand or guaranteed future profit.
Contract schedules, customer approvals, project completion and collection terms influence the conversion of backlog into earnings and cash flows.
Private Customers Account for 78% of the Order Book
The reported order backlog was distributed across several customer categories.
Private-sector customers accounted for approximately 78% of the total, while central utilities and public sector undertakings contributed about 20%.
State utilities represented the remaining 2%.
The distribution shows the importance of private-sector demand within the company’s order pipeline.
However, the composition also creates exposure to the spending plans and project execution capabilities of private customers.
Investors should monitor customer concentration and payment terms in addition to the headline backlog.
What Gives GE Vernova T&D India a Competitive Advantage?
GE Vernova T&D India operates in the power transmission and distribution equipment industry and is associated with GE Vernova’s global electrification business.
Its product portfolio includes power transformers, gas-insulated switchgear (GIS), air-insulated switchgear (AIS), grid automation systems and other transmission infrastructure solutions.
The company’s competitive position can be assessed through several characteristics.
Technical Expertise in Grid Infrastructure
High-voltage electrical transmission projects require specialised engineering, product reliability and compliance with stringent technical specifications.
Established equipment suppliers with relevant technology and execution experience may be better positioned to participate in complex tenders.
Exposure to Multiple Grid Technologies
The company’s portfolio spans transformers, switchgear and automation solutions.
This provides exposure to different areas of electricity network investment instead of relying on a single product category.
Association With a Global Technology Group
Its relationship with GE Vernova may provide access to technical expertise and international business opportunities.
However, the relationship also introduces considerations such as related-party transactions, dependence on group-linked orders and the timing of international projects.
Opportunities in Transmission Modernisation
Electricity demand growth, renewable energy integration and industrial electrification can create requirements for transmission expansion and modernisation.
High-voltage transmission equipment and grid automation systems are relevant to these requirements.
Nevertheless, exposure to an attractive industry does not automatically guarantee superior profitability or stock-market performance.
Competition, execution quality, working capital and valuations remain important.
Why India’s Transmission Sector Offers Long-Term Opportunities
India’s electricity network must accommodate changing patterns of power generation and consumption.
Renewable energy projects are often located far from major demand centres, increasing the importance of long-distance transmission infrastructure.
HVDC systems can be relevant for transferring large amounts of electricity across long distances under suitable technical and economic conditions.
At the same time, growing industrial electricity requirements and data centre development can increase demand for reliable power infrastructure.
Grid digitalisation and automation may support network management, fault detection and system reliability.
These structural requirements create potential demand for equipment and engineering services.
However, the actual revenue opportunity for GE Vernova T&D India depends on which projects are awarded, the company’s participation in those projects and the timing of execution.
Key Risks Investors Should Consider
Despite strong quarterly financial performance and positive brokerage recommendations, GE Vernova T&D India faces several risks.
Project execution risk: Delays in major transmission projects can defer revenue recognition and affect working capital requirements.
Export order uncertainty: International business may be influenced by customer decisions, parent-group order allocations, regulatory changes and trade conditions.
Margin normalisation: The reported Q2 EBITDA margin of 27.1% exceeds management’s approximately 25% full-year guidance. Future quarters may therefore show lower margins.
Valuation risk: Strong earnings growth expectations may already be reflected in the market price, potentially limiting returns if forecasts are missed.
Order concentration: Large contracts can create variability in quarterly orders, execution and profitability.
Working capital and cash flow: Project-based businesses may face delays between equipment production, invoicing and customer payments.
Related-party exposure: Investors should examine the commercial terms and financial significance of transactions involving the wider GE Vernova group.
These factors help explain why brokerage target prices differ despite broadly positive views on India’s transmission infrastructure opportunity.
Should Investors Buy GE Vernova T&D India at ₹4,102?
The reported brokerage targets suggest a wide range of possible outcomes.
Nomura’s ₹6,090 target reflects its optimistic assumptions about earnings growth, stronger exports and long-term opportunities.
JPMorgan and Citi have adopted positive views with ₹5,400 targets.
Jefferies’ ₹4,390 target suggests a more cautious assessment, particularly regarding export visibility and order timing.
Investors should not assume that the highest target is necessarily the most accurate.
Before making an investment decision, it is important to review the company’s valuation relative to expected earnings, order execution, competitive position and the consistency of free cash flow.
Financial results, order announcements and management guidance should be evaluated alongside the assumptions underlying each brokerage’s recommendation.
What Should Investors Watch Next?
The company’s future performance will depend on several important developments.
Investors should monitor whether order inflows remain strong during the second half of FY27 and whether the existing ₹21,443 crore backlog converts into profitable revenue.
The timing of the proposed Barmer HVDC opportunity and progress on other large transmission projects will also matter.
Export orders, the status of the prospective US data centre-related transaction and the sustainability of EBITDA margins deserve particular attention.
Further clarity on management’s long-term growth ambitions could help investors assess the reasonableness of current earnings expectations.
Conclusion
GE Vernova T&D India’s strong Q2 FY27 financial performance, substantial order backlog and exposure to India’s electricity transmission expansion have attracted positive assessments from major global brokerages.
Nomura sees the highest potential upside among the four cited recommendations, with a ₹6,090 target representing approximately 48.5% upside from the reported ₹4,102 reference price.
JPMorgan and Citi remain constructive, while Jefferies has taken a more cautious position.
For investors, the key question is whether the company can sustain strong profitability while converting large domestic and international opportunities into completed projects.
The next few quarters will be important in assessing earnings growth, order execution and the durability of the company’s margin performance.