

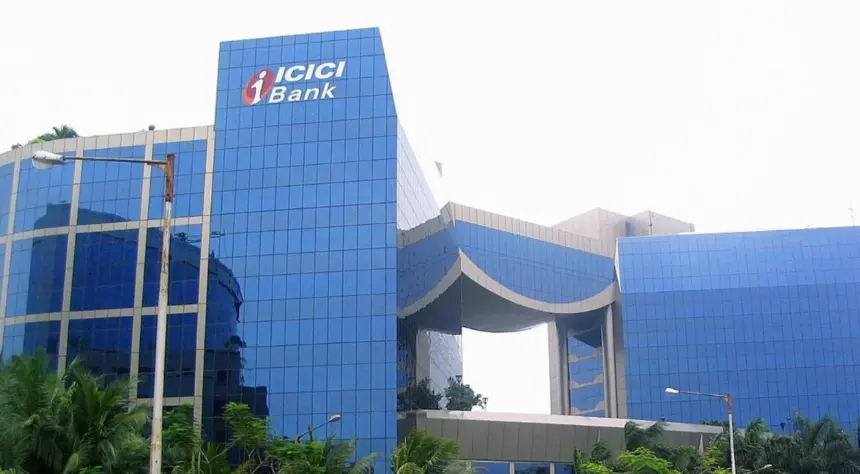
ICICI Bank reported a 20.1% year-on-year increase in standalone net profit to ₹14,843 crore for the July–September quarter of FY2026–27, according to the figures provided. Higher net interest income, growth in advances and deposits, and lower provisions supported the performance, while the bank’s net interest margin moderated.
ICICI Bank’s second-quarter results for FY2026–27 highlight continued growth in its lending business alongside an improvement in reported asset quality. The lender’s consolidated net profit also increased, while net interest income and core operating profit recorded double-digit growth.
The figures indicate a quarter in which business expansion and lower provisions contributed to earnings growth. However, the decline in net interest margin suggests that lending profitability remains an important metric to monitor in the coming quarters.
The financial figures in this report should be checked against the bank’s official quarterly results and stock exchange disclosures before publication.
See more of our coverage in your search results.
Add INDYASTORY on GoogleICICI Bank Q2 Results FY27: Key Financial Highlights
According to the supplied results, the bank reported the following performance for the quarter ended September 30, 2026.
| Financial metric | Q2 FY27 | Year-on-year change |
|---|---|---|
| Standalone net profit | ₹14,843 crore | +20.1% |
| Consolidated net profit | ₹16,333.18 crore | +22.28% |
| Net interest income | ₹25,339 crore | +17.7% |
| Core operating profit | ₹20,805 crore | +21.8% |
| Profit before tax | ₹19,724 crore | +20.4% |
| Net interest margin | 4.18% | Down from 4.30% |
| Gross NPA ratio | 1.20% | Down from 1.58% |
| Net NPA ratio | 0.30% | Down from 0.39% |
Source: Figures supplied for this report; verify against ICICI Bank’s official exchange filing before publication.
Standalone Net Profit Increases 20.1%
ICICI Bank’s standalone net profit rose to ₹14,843 crore in the September quarter, representing a 20.1% increase from the corresponding period a year earlier.
On a consolidated basis, net profit climbed 22.28% to ₹16,333.18 crore from ₹13,357.06 crore in the year-ago quarter.
Standalone and consolidated earnings measure different aspects of a company’s financial performance. Standalone results reflect the bank as an individual legal entity, while consolidated results incorporate relevant subsidiaries and other entities included in its consolidated financial statements.
See more of our coverage in your search results.
Add INDYASTORY on GoogleThe distinction is important when comparing results across periods or assessing the contribution of the wider group.
The reported increase in earnings coincided with stronger net interest income, higher core operating profit and a reduction in provisions and contingencies.
Net Interest Income Rises 17.7% to ₹25,339 Crore
Net interest income (NII), which represents the difference between interest earned on loans and investments and interest paid on deposits and borrowings, increased 17.7% year-on-year to ₹25,339 crore.
See more of our coverage in your search results.
Add INDYASTORY on GoogleIn the corresponding quarter last year, NII stood at ₹21,529 crore.
Growth in net interest income is an important indicator for banks because it reflects the performance of their core lending and deposit-taking operations. Its trajectory depends on factors such as loan growth, deposit costs, lending rates and the composition of the balance sheet.
ICICI Bank’s reported NII growth was accompanied by a 21.8% increase in core operating profit to ₹20,805 crore. Profit before tax rose 20.4% to ₹19,724 crore.
Together, these measures provide a broader view of the bank’s operating performance beyond its headline net profit.
Net Interest Margin Moderates to 4.18%
Despite the increase in net interest income, ICICI Bank’s net interest margin (NIM) declined to 4.18% in Q2 FY27.
The margin stood at 4.30% in the corresponding quarter of the previous financial year and 4.36% in the preceding quarter.
NIM measures the spread between interest income generated by a bank’s earning assets and the interest expense associated with its funding, relative to those assets. It is widely used to assess the efficiency and profitability of a bank’s core intermediation business.
A lower margin does not necessarily indicate weaker overall earnings. A bank can increase net interest income through higher business volumes even when its margin contracts.
Nevertheless, the direction of NIM remains important because sustained pressure can affect future earnings if it is not offset by loan growth, operating efficiencies or other income sources.
Investors will therefore be watching whether the bank can maintain its earnings momentum while managing funding costs and competitive pressure on lending rates.
Advances Grow 30%; Adjusted Growth Stands at 24.1%
ICICI Bank’s advances increased 30% year-on-year to ₹18.32 lakh crore as of September 30, according to the supplied figures.
However, the reported growth rate was lower after excluding loans extended by the bank’s international branches against foreign currency non-resident bank deposits under a concessional swap scheme.
On this adjusted basis, advances growth stood at 24.1%.
The distinction offers a more detailed view of the bank’s underlying lending expansion by separating the specified FCNR-B-related balances from the reported total.
Loan growth can support future interest income, but its quality and profitability are equally important. Investors should also assess the distribution of lending across retail, business and corporate borrowers, as well as the associated credit risks and funding requirements.
The bank’s ability to maintain prudent underwriting standards while expanding its loan book will remain a key factor in determining the sustainability of earnings growth.
Deposits Rise 27.1% to ₹20.50 Lakh Crore
Deposits increased 27.1% year-on-year to ₹20.50 lakh crore at the end of September.
Excluding FCNR-B deposits, the reported growth rate stood at 17%.
Deposits are a crucial source of funding for banks because they support lending and influence the cost of maintaining the balance sheet. Growth in deposits can help a lender finance additional advances, although the composition and pricing of those deposits also matter.
The difference between the reported and adjusted growth rates is relevant when assessing the bank’s underlying funding trends.
Investors should monitor deposit growth alongside advances, the mix of current and savings account deposits, term deposits and the bank’s cost of funds. Faster lending growth is more sustainable when supported by an appropriate and competitively priced funding base.
ICICI Bank Asset Quality Improves as Gross NPA Falls to 1.20%
The bank reported an improvement in asset quality during the quarter.
Its gross non-performing asset (NPA) ratio declined to 1.20% as of September 30, compared with 1.58% a year earlier and 1.38% in the preceding quarter.
The net NPA ratio also fell to 0.30% from 0.39% in the corresponding period last year.
Gross NPAs represent loans classified as non-performing before deducting provisions, while net NPAs reflect the remaining exposure after accounting for applicable provisions.
Lower NPA ratios generally indicate an improvement in the proportion of problem loans relative to the loan book. However, these ratios should be assessed alongside fresh slippages, recoveries, write-offs, restructuring and the composition of the bank’s credit portfolio.
The decline in both gross and net NPA ratios is a positive reported development, although future asset quality will depend on borrower repayment capacity, economic conditions and lending standards.
Provisions Decline to ₹850.69 Crore
ICICI Bank’s provisions and contingencies declined to ₹850.69 crore from ₹914.11 crore in the year-ago quarter.
Provisions are amounts recognised to account for expected or identified losses and other specified contingencies. Their level can influence reported profit, particularly when credit costs change materially between periods.
Lower provisions can support earnings, but they should not be interpreted in isolation. A complete assessment requires examining the bank’s credit costs, provision coverage, new loan defaults and management’s assessment of potential risks.
The combination of lower provisions and improving reported NPA ratios provides useful context for understanding the quarter’s profit growth.
Capital Adequacy Ratio Improves to 16.68%
The bank’s overall capital adequacy ratio stood at 16.68% as of September 30, compared with 15.76% a year earlier.
Capital adequacy measures the capital available to absorb potential losses relative to risk-weighted assets. It is a key indicator of a bank’s financial resilience and its capacity to support business growth while meeting regulatory requirements.
A higher reported ratio can provide a stronger capital buffer, although the implications depend on the composition of capital, the growth of risk-weighted assets and applicable regulatory requirements.
As lending expands, investors will continue to monitor capital adequacy alongside credit quality, profitability and funding conditions.
Consolidated Assets Rise 22.6%
On a consolidated basis, ICICI Bank’s total assets grew 22.6% year-on-year to ₹32.93 lakh crore at the end of September.
Growth in total assets reflects the expansion of the overall balance sheet, but its quality and composition are important. Investors should examine how much growth comes from loans, investments and other assets, and how this expansion is funded.
The relationship between asset growth, deposit mobilisation, capital adequacy and profitability will be important in determining whether the bank can sustain its operating performance.
What ICICI Bank’s Q2 Performance Means for Investors
The supplied Q2 FY27 figures point to several developments: higher standalone and consolidated profit, strong growth in net interest income, expansion in advances and deposits, and lower reported NPA ratios.
At the same time, the moderation in net interest margin highlights a factor that warrants attention. The pace of future earnings growth will depend not only on business expansion but also on funding costs, lending yields, operating expenses and credit quality.
Investors assessing the results should compare the reported numbers with the bank’s official financial statements, management commentary and previous quarters. They should also distinguish between year-on-year growth and sequential changes, as each provides a different perspective on performance.
Overall, the reported quarter combines earnings growth with improving asset-quality indicators, while margin trends and the sustainability of credit expansion remain important areas to watch.