

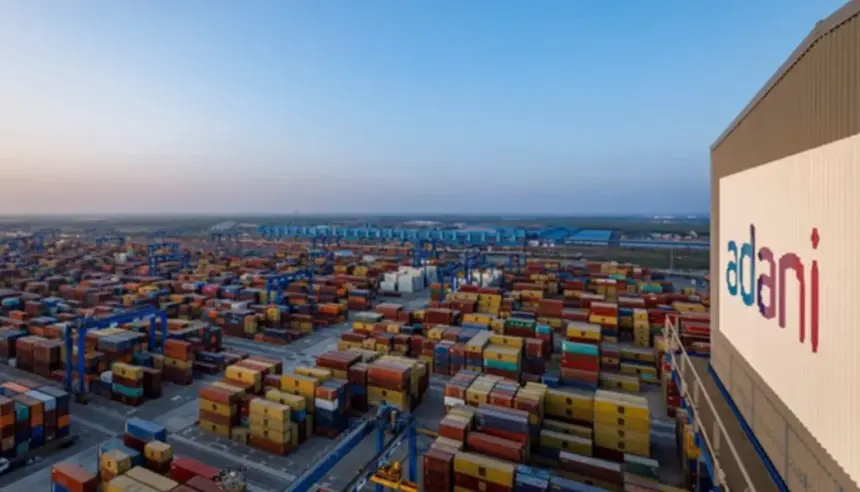
Adani Ports and Special Economic Zone (APSEZ) has agreed to acquire Netherlands-headquartered Evos B.V. from Igneo Infrastructure Partners in an all-cash transaction carrying an enterprise value of €2.56 billion. The proposed acquisition will give the Adani Group company eight liquid storage terminals across five European countries and add 6.3 million cubic metres of storage capacity to its international infrastructure portfolio.
Adani Ports and Special Economic Zone Limited (APSEZ) is preparing for a major expansion in Europe through its proposed acquisition of Evos B.V., a Netherlands-based operator of liquid bulk storage infrastructure.
The transaction, valued at €2.56 billion on an enterprise-value basis, will give APSEZ full ownership of Evos, subject to regulatory approvals and other closing conditions.
The agreement marks a significant step in the company’s strategy to develop a diversified global transport and logistics platform.
See more of our coverage in your search results.
Add INDYASTORY on GoogleEvos operates liquid storage terminals in the Netherlands, Germany, Spain, Belgium and Malta, serving customers across the energy, industrial, chemical and commodity trading sectors.
According to the transaction details supplied, the addition of Evos will expand APSEZ’s worldwide presence to 28 ports and terminals across 10 countries.
The acquisition also provides exposure to infrastructure handling conventional petroleum products and alternative fuels, including sustainable aviation fuel, biofuels and methanol.
For APSEZ, the strategic attraction lies in the combination of geographic expansion, recurring infrastructure revenue and access to important European energy hubs.
Adani Ports–Evos Acquisition: Key Deal Details
| Particulars | Reported details |
|---|---|
| Acquiring company | Adani Ports and Special Economic Zone (APSEZ) |
| Target company | Evos B.V. |
| Seller | Igneo Infrastructure Partners |
| Stake being acquired | 100% |
| Enterprise value | €2.56 billion |
| Equity value | €1.18 billion |
| Enterprise value/EBITDA | 11.7 times, based on CY2025 EBITDA |
| Acquisition financing | Debt-funded |
| Financing underwriter | MUFG |
| Financing commitment | Up to €2.8 billion |
| Liquid storage terminals | 8 |
| European countries | 5 |
| Combined storage capacity | 6.3 million cubic metres |
| Expected APSEZ global network | 28 ports and terminals across 10 countries |
| Transaction status | Subject to approvals and consultation requirements |
Figures reflect the supplied transaction announcement and should be checked against APSEZ’s official stock exchange disclosures.
See more of our coverage in your search results.
Add INDYASTORY on GoogleWhat Is Evos B.V. and Why Does APSEZ Want to Acquire It?
Evos is a European liquid storage infrastructure business headquartered in the Netherlands.
Its terminals provide facilities for storing and handling products such as gasoline, gasoil, marine fuels, jet fuel, chemicals and selected alternative fuels.
These facilities form an important part of the energy supply chain.
See more of our coverage in your search results.
Add INDYASTORY on GoogleProducers, trading companies and industrial customers need storage infrastructure to manage shipments, inventories and product distribution.
Liquid bulk terminals typically include large storage tanks, loading infrastructure, marine berths and pipeline connections.
Unlike container ports, which handle packaged cargo, liquid storage terminals specialise in products that are transported and stored in bulk.
This makes Evos a complementary infrastructure asset for APSEZ.
The acquisition would extend the Indian company’s presence beyond traditional port handling and logistics operations into a wider range of energy storage services.
According to the supplied report, Evos is Europe’s second-largest independent liquid storage operator. That market ranking should be confirmed against a dated industry source before publication.
Evos Operates Eight Terminals Across Five European Countries
The geographical reach of Evos is one of the transaction’s most important features.
Its eight terminals are located across:
- Netherlands
- Germany
- Spain
- Belgium
- Malta
These facilities provide access to important shipping, industrial and energy distribution markets.
The portfolio includes operations in the Amsterdam-Rotterdam-Antwerp region, commonly known as ARA, as well as Hamburg and the Mediterranean.
The ARA region is particularly significant because it connects some of Europe’s busiest ports with refining, storage, trading and industrial networks.
Evos’ presence in these locations could provide APSEZ with a position in established European energy logistics corridors.
Storage tanks, berths and pipeline connections
The Evos portfolio includes 452 storage tanks and 63 vessel and barge berths, according to the supplied transaction information.
Its facilities are also connected to pipeline infrastructure, including links associated with Schiphol Airport and the Central Europe Pipeline System.
These connections allow certain products to move between storage terminals and wider distribution networks.
In calendar year 2025, Evos reportedly handled approximately 37 million metric tonnes of throughput.
The addition of this infrastructure would allow APSEZ to participate in more segments of international liquid bulk logistics.
However, the transaction’s contribution to APSEZ’s consolidated cargo volumes will depend on the company’s reporting methodology following completion.
Evos Financial Performance: Revenue, EBITDA and Margins
Evos enters the transaction with a reported record of substantial operating earnings.
According to the supplied financial figures, the company generated revenue of €392 million during calendar year 2025.
Its earnings before interest, tax, depreciation and amortisation (EBITDA) reached €219 million.
That translates into an EBITDA margin of approximately 56%.
| Evos financial indicator | CY2025 |
|---|---|
| Revenue | €392 million |
| EBITDA | €219 million |
| EBITDA margin | Approximately 56% |
| Commercial occupancy | Approximately 99% |
| Throughput | 37 million metric tonnes |
An EBITDA margin of 56% indicates that Evos generated approximately €56 in EBITDA for every €100 of reported revenue.
However, EBITDA is not the same as net profit or free cash flow.
The metric excludes several expenses, including depreciation, financing costs and taxes.
For capital-intensive infrastructure businesses, those costs can be significant.
A complete assessment of Evos’ profitability would therefore require information about capital expenditure, debt servicing, depreciation and cash generation.
Why Evos’ 99% Occupancy Matters
Another notable feature of Evos’ business is its reported average commercial occupancy of 99%.
High occupancy suggests that a substantial proportion of the company’s available storage capacity was commercially contracted or utilised under the relevant reporting definition.
For infrastructure operators, stable customer demand can contribute to more predictable revenue.
Evos also reportedly benefits from take-or-pay arrangements and contracts linked to consumer price inflation.
What are take-or-pay contracts?
Under a take-or-pay structure, a customer generally agrees to pay for a contracted level of service or capacity, subject to the specific contractual terms.
This can provide revenue visibility even when actual utilisation varies.
Contracts with inflation-linked pricing may also help protect revenue against certain increases in operating costs.
However, such arrangements do not eliminate commercial risk.
Customer creditworthiness, contract expiry, regulatory developments and future demand can still affect earnings.
The significance for APSEZ is that Evos could add a business with a different revenue profile from some conventional port operations.
€2.56 Billion Enterprise Value vs €1.18 Billion Equity Value: What’s the Difference?
The acquisition has two important valuation figures.
The reported enterprise value is €2.56 billion, while the equity value is €1.18 billion.
These amounts measure different aspects of the transaction.
Enterprise value represents the value of a business to capital providers, generally incorporating equity value and net financial debt, subject to the deal’s specific adjustments.
Equity value represents the amount attributable to shareholders under the agreed valuation structure.
Based on the supplied figures, the difference between the enterprise value and equity value is approximately €1.38 billion.
That difference should not automatically be described as the exact amount of debt APSEZ will assume without reviewing the transaction’s debt, cash and other closing adjustments.
The deal’s reported enterprise value-to-EBITDA multiple is approximately 11.7 times.
Using Evos’ €219 million CY2025 EBITDA, the ratio is broadly consistent with the reported €2.56 billion enterprise valuation.
Whether that multiple represents an attractive purchase price depends on factors such as comparable infrastructure valuations, future earnings growth, asset quality, investment requirements and financing costs.
How Will Adani Ports Finance the Evos Acquisition?
The proposed transaction will be funded through debt, according to the supplied announcement.
MUFG has been identified as the sole underwriter, with financing commitments of up to €2.8 billion.
This commitment provides an important element of financing support for the deal.
However, the full €2.8 billion commitment should not be interpreted as the exact amount that will ultimately be drawn.
The final financing structure may depend on transaction expenses, refinancing arrangements and other deal requirements.
Debt-funded acquisitions can allow buyers to preserve existing cash resources.
They can also increase financial obligations through interest payments and principal repayments.
For investors, the important question is whether the acquired business can produce sufficient cash flow to support its financing requirements while contributing to the wider group’s earnings.
What Karan Adani Said About the Acquisition
Karan Adani, Managing Director of APSEZ, described the agreement as an important step in the company’s international expansion.
According to the supplied announcement, he said the transaction supports APSEZ’s long-term ambition of handling one billion tonnes of cargo and establishing a more integrated global transport platform.
He also emphasised the company’s interest in supporting Europe’s energy transition while maintaining financial discipline.
The strategic message is that APSEZ views Evos as more than an expansion in geographical coverage.
It is also a means of entering established energy storage markets and developing a broader infrastructure portfolio.
The comments should be matched against the company’s original announcement before being reproduced as a direct quotation.
Why the Evos Deal Could Improve APSEZ’s Earnings Diversification
APSEZ operates infrastructure across different geographical markets and cargo segments.
Acquiring Evos would add storage assets serving energy and industrial customers in Europe.
This could reduce the company’s relative dependence on individual markets or cargo categories, although the degree of diversification would need to be assessed using consolidated financial data.
The supplied report states that Evos’ 56% EBITDA margin is higher than the 44.8% EBITDA margin recorded by APSEZ’s international ports business during the first half of FY2027.
The difference suggests that Evos has a relatively high operating margin within the reported comparison.
However, this does not automatically establish that the transaction will increase APSEZ’s consolidated net profit margin.
Acquisition financing costs, depreciation, transaction expenses and accounting adjustments can influence the final results.
A more complete analysis would examine how Evos contributes to consolidated earnings and cash flow after completion.
APSEZ’s Debt Position After the Proposed Acquisition
The transaction is expected to increase APSEZ’s financial leverage.
According to the supplied figures, the combined business would have a pro forma net debt-to-EBITDA ratio of approximately 2.76 times, using APSEZ’s FY2026 and Evos’ CY2025 financial information.
APSEZ expects the ratio to moderate towards approximately 2.5 times by FY2027.
These are company projections based on assumptions and are not guaranteed outcomes.
What does net debt-to-EBITDA measure?
Net debt-to-EBITDA is commonly used to assess financial leverage.
It compares a company’s net financial debt with its annual EBITDA.
A higher ratio can indicate a larger debt burden relative to operating earnings.
However, the appropriate level varies across industries.
Infrastructure companies may have relatively stable contracted revenue streams, which can support higher debt levels than businesses with unpredictable earnings.
Investors should examine interest coverage, cash generation, debt maturities and capital expenditure alongside the leverage ratio.
APSEZ’s Financial Position Before the Deal
As of September 30, 2026, APSEZ reportedly held cash balances of ₹12,502 crore.
Its international ports business recorded revenue of ₹3,586 crore during the first half of FY2027.
EBITDA for the same segment reached ₹1,608 crore, representing a margin of approximately 44.8%.
| APSEZ international ports business | H1 FY2027 |
|---|---|
| Revenue | ₹3,586 crore |
| EBITDA | ₹1,608 crore |
| EBITDA margin | 44.8% |
| Cargo volumes | 47 MMT |
| Previous comparable volumes | 17 MMT |
| Group cash balance at September 30, 2026 | ₹12,502 crore |
The reported increase in international volumes reflects contributions from several operations.
These include Colombo West International Terminal, Tanzania operations and NQXT Australia.
The figures indicate a substantial expansion of the group’s international business during the period covered.
However, cash balances and EBITDA alone do not establish how much additional debt the business can comfortably support.
That assessment requires examination of consolidated obligations and future investment requirements.
Evos Could Strengthen Adani Ports’ Position in Europe’s Energy Transition
The Evos portfolio handles both conventional petroleum products and fuels associated with the energy transition.
Its products include gasoline, gasoil, marine fuels and jet fuel.
The supplied report also identifies sustainable aviation fuel, biofuels, methanol and bioethanol among the products handled by the company’s infrastructure.
This diversity may provide opportunities as Europe’s fuel supply chains evolve.
For example, sustainable aviation fuel is being developed to reduce lifecycle greenhouse gas emissions associated with aviation compared with conventional fossil jet fuel, depending on its production pathway.
Biofuels and alternative marine fuels are also relevant to changes in transportation and industrial energy use.
However, storage infrastructure does not itself guarantee that all fuels handled are environmentally sustainable.
The environmental impact depends on product characteristics, production methods, actual demand and applicable regulations.
For APSEZ, the commercial opportunity lies in owning infrastructure that can serve different types of liquid cargo as market requirements change.
What Are the Strategic Benefits for Adani Ports?
The proposed acquisition offers several potential advantages.
European expansion: APSEZ would gain immediate access to eight terminals in five countries rather than building an entirely new network from the ground up.
Storage capacity: The company would add 6.3 million cubic metres of liquid storage infrastructure.
Customer diversification: Evos serves energy majors, industrial businesses, chemical companies and commodity traders.
Contracted revenue: Take-or-pay and inflation-linked contracts may contribute to more predictable earnings.
Alternative fuels exposure: The portfolio offers infrastructure associated with conventional and emerging liquid fuel markets.
Operating scale: The transaction would increase APSEZ’s international assets and expand its global network.
These benefits depend on successful completion and integration of the acquisition.
What Risks Should Investors Consider?
Despite the strategic opportunities, the proposed transaction involves several risks.
1. Acquisition financing
Debt funding can increase interest expenses and financial leverage.
Changes in financing conditions may affect the economic returns from the acquisition.
2. Regulatory approvals
The transaction remains subject to relevant approvals and works council consultation requirements.
Delays or conditions imposed during the approval process could affect the closing timetable.
3. European market conditions
Energy demand, industrial activity and infrastructure regulations can influence storage utilisation and revenue.
4. Energy transition uncertainty
Alternative fuel adoption may evolve at a different pace from current expectations.
Infrastructure operators must adapt their facilities and investment decisions accordingly.
5. Integration and execution
Managing assets across different jurisdictions can involve operational, legal and compliance complexities.
APSEZ will need to maintain established customer relationships and operating standards while integrating the new business.
When Will the Adani Ports–Evos Deal Be Completed?
The supplied announcement does not establish a definitive closing date.
The transaction remains subject to regulatory approvals, other conditions and works council consultation.
Consequently, Evos should not yet be described as a completed acquisition or an existing wholly owned subsidiary of APSEZ.
Investors should monitor official company disclosures for updates on approvals, financing and closing.
The actual date on which Evos’ financial results are consolidated will depend on the transaction’s completion and applicable accounting rules.
What Does the Acquisition Mean for APSEZ Shareholders?
For APSEZ shareholders, the proposed transaction creates a combination of potential growth opportunities and financial considerations.
The acquisition could expand the company’s international earnings base and provide exposure to European liquid storage infrastructure.
Evos’ reported high EBITDA margin and contracted revenue arrangements may support earnings visibility.
However, investors should also consider the acquisition multiple, additional leverage, financing costs and integration requirements.
A strategically attractive acquisition does not necessarily guarantee a positive share-price response.
The market’s assessment will depend on whether future financial results justify the cost and risks of the transaction.
Conclusion: Adani Ports Takes a Major Step Towards a Global Infrastructure Platform
Adani Ports’ proposed €2.56 billion acquisition of Evos represents a significant international expansion into European liquid storage infrastructure.
The transaction would add eight terminals, 452 storage tanks and 6.3 million cubic metres of capacity across five countries.
It would also provide access to established energy distribution hubs and infrastructure handling both conventional and alternative fuels.
Evos’ reported 56% EBITDA margin, high occupancy and contracted revenue arrangements are important features of the investment case.
At the same time, the debt-funded structure and regulatory requirements create financial and execution considerations.
For APSEZ, the long-term value of the transaction will depend on the ability to integrate Evos, preserve its cash generation and manage the additional financial obligations.
If completed, the deal would strengthen APSEZ’s position as a diversified international ports and logistics infrastructure operator.
Financial disclaimer: This article is for informational purposes and does not constitute investment advice or a recommendation to buy, sell or hold APSEZ shares.