

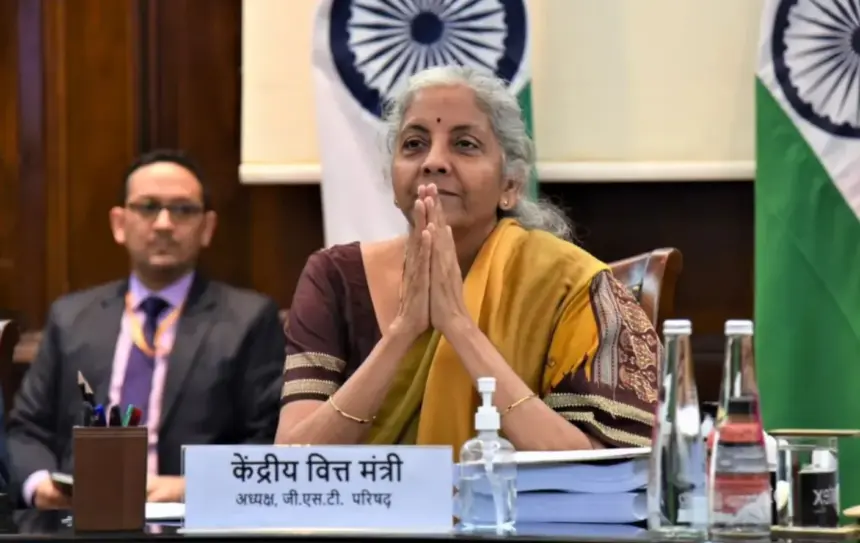
The 57th GST Council meeting is underway in New Delhi on Thursday, October 8, with the government expected to focus on simplifying tax procedures and strengthening compliance rather than making broad changes to GST rates.
The meeting at Bharat Mandapam is expected to consider a range of proposals covering input tax credit, refunds, registration and enforcement, according to the information supplied.
A major GST rate overhaul is not expected to be on the agenda. Instead, the proposed measures are aimed at making the indirect tax system more predictable for businesses and reducing procedural hurdles for taxpayers.
Here are the key reforms and expectations being discussed.
See more of our coverage in your search results.
Add INDYASTORY on Google1. No major GST rate changes expected
The Council is not expected to announce broad changes to the existing GST rate structure at the meeting.

Instead, only limited rationalisation and clarification issues may be considered.
The approach would keep the focus of the meeting on administrative and structural reforms rather than another large-scale rate revision.
2. GST rate changes could become an annual exercise
One proposal under discussion could make future GST rate changes more predictable by considering them once a year, with revised rates taking effect from April 1.
Such a system could give companies more time to prepare pricing, accounting and compliance systems for changes in indirect taxation.
See more of our coverage in your search results.
Add INDYASTORY on GoogleFor businesses, greater predictability can be particularly important where GST changes affect contracts, inventory, invoices and consumer prices.
3. Input tax credit protection may be expanded
A significant proposal concerns input tax credit (ITC).
Under the suggested framework, a buyer that holds a valid invoice, has received the goods and has paid the supplier—including the applicable GST—could potentially retain its credit even when a supplier further up the transaction chain defaults.
See more of our coverage in your search results.
Add INDYASTORY on GoogleThe proposal is aimed at protecting genuine purchasers from losing tax credits because of non-compliance elsewhere in the supply chain.
Such a change could also reduce uncertainty for businesses that follow GST requirements but depend on compliance by suppliers.
4. More business expenses could qualify for ITC
The proposed reforms could also widen the range of business expenses eligible for input tax credit.
Some expenditure currently outside the credit chain may be brought within the system, according to the supplied information.
The proposals also seek to address situations where the same service is resold within the same line of business, potentially reducing instances of unintended double taxation.
The precise scope of any expanded credit provisions would depend on the final Council decision.
5. GST refunds could become faster
Another major item on the agenda is the processing of GST refund claims.
At present, refund applications reportedly take about 25 days on average to process.
Under the proposed system, applications could receive acknowledgement within 10 days, while as much as 90% of eligible refunds could potentially be released following a risk assessment.
Faster refunds would be especially relevant to exporters and businesses where significant working capital is locked up in tax credits or refund claims.
6. Refund processing may become more automated
The Council could also consider greater use of automated data matching.
Under the proposal, refund-related information could be pulled directly from customs and banking systems, reducing the amount of documentation companies need to submit manually.
The idea is to use information already available with government systems rather than requiring taxpayers to repeatedly provide the same records.
Greater automation could reduce processing time and administrative costs while allowing officials to concentrate on higher-risk applications.
7. GST refund coverage could be widened
The proposed refund framework may also cover a broader set of transactions.
The changes under consideration could extend refund eligibility to services and plant and machinery, along with provisions relevant to exporters using duty drawback mechanisms.
Wider coverage could potentially simplify the treatment of businesses with more complex export and investment structures.
8. Arrest provisions could be reconsidered
The GST Council may also examine the use of arrest provisions under GST law.
One proposal could remove or substantially reduce reliance on arrest as an enforcement mechanism, with authorities instead using civil measures such as recovery of tax, interest and penalties.
Serious offences could still remain subject to prosecution.
Any such change would represent an important shift in the balance between GST enforcement and taxpayer protection, but the final legal position will depend on the Council’s decision and subsequent legislative or administrative action.
9. Prosecution threshold may rise to Rs 5 crore
Another proposal could increase the threshold for prosecution from ₹1 crore to ₹5 crore.
The change would potentially mean that prosecution is reserved for more serious cases, while smaller disputes are handled through tax recovery, interest and penalties.
The proposal would need to be formally approved and implemented before becoming part of the applicable GST framework.
10. Smaller taxpayers could receive compliance relief
The reform package could also include measures designed to reduce the compliance burden on smaller businesses.
Possible measures include waiving late fees for delayed returns, rationalising general penalties and speeding up GST registration for eligible applicants.
For small and medium-sized businesses, such measures could reduce the cost of dealing with procedural defaults while allowing enforcement resources to focus on larger or more serious violations.
GST collections and effective tax rate in focus
The proposed reforms come against the backdrop of changes in GST revenue and the effective tax burden.
According to the figures supplied, taxable supplies increased 25.8% year-on-year between October and July, while gross tax liability rose 13.6%.
At the same time, the effective tax rate on domestic taxable supplies declined to 13.13% from 14.55%.
The figures suggest that the GST system continues to generate higher volumes of taxable activity even as the effective rate on domestic supplies has moderated.
Why the October GST Council meeting matters
The 57th GST Council meeting is important less for a new rate structure and more for the potential direction of GST administration and compliance reform.
Input tax credit protection could reduce risk for compliant businesses, while faster and automated refunds could improve working-capital efficiency.
Changes involving arrest and prosecution could also alter how the GST law deals with serious and procedural violations.
For taxpayers, however, the key distinction is between proposals discussed at the meeting and measures that are formally approved and notified.
The Council’s final decisions, followed by the required legal and administrative notifications, will determine which of these reforms actually become part of India’s GST regime.