

Disagreement over N Chandrasekaran’s reappointment has raised questions about shareholder rights, board procedures and the authority needed to lead India’s largest business group.
The leadership dispute at Tata Sons has brought a fundamental corporate-governance question into focus: how should a professionally managed holding company resolve disagreements between its board and its controlling shareholders?
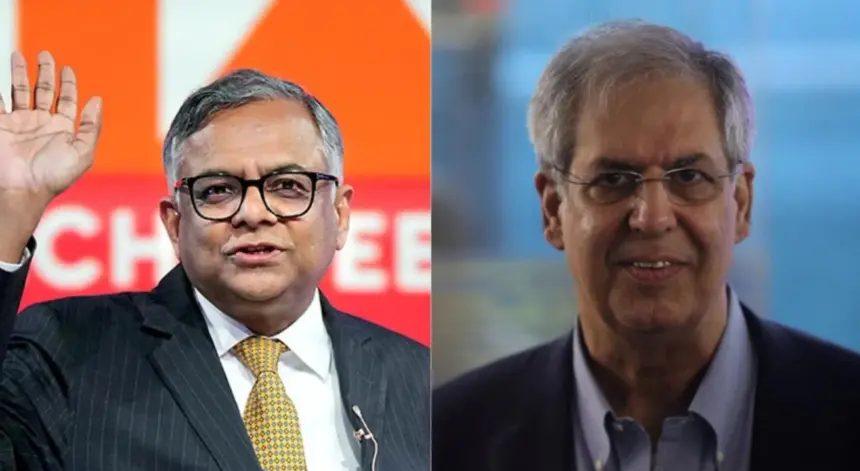
Tata Trusts Chairman Noel Tata has challenged the resolution to reappoint N Chandrasekaran as Tata Sons chairman beyond February 2027, according to an October 26 PTI report. The challenge concerns the September 17 board meeting and the procedures used to approve the appointment.
PTI reported that Noel Tata opposed the resolution, while Venu Srinivasan, the other Tata Trusts nominee on the board, supported it. The disagreement means the dispute extends beyond a simple division between shareholders and professional management. The controlling shareholder’s representatives themselves took different positions.
See more of our coverage in your search results.
Add INDYASTORY on GoogleHow Tata Sons and Tata Trusts are connected
Tata Sons is the principal investment holding company and promoter of Tata companies. Philanthropic trusts hold 66% of its equity, according to the group’s official website.
That ownership structure connects the group’s commercial performance with a broader philanthropic purpose. Tata Trusts says dividends received from Tata Sons support its charitable work.
However, ownership of the holding company should not be confused with direct management of every business. Tata states that individual group companies operate under the guidance and supervision of their own boards.
This creates several distinct responsibilities: trustees oversee charitable institutions, Tata Sons makes holding-company decisions, and operating-company boards oversee their respective businesses.
Effective governance depends on those responsibilities remaining clear.
See more of our coverage in your search results.
Add INDYASTORY on GoogleWhy the nominee directors’ votes matter
The immediate disagreement involves the interpretation of Tata Sons’ Articles of Association and the affirmative support required from Tata Trusts-nominated directors.
Tata Trusts has argued that support from one of its two nominees does not meet the relevant requirement. It has also disputed whether a chairperson’s casting vote can resolve that particular disagreement.
Tata Sons, meanwhile, announced that its board had approved Chandrasekaran’s reappointment by a majority vote. Reporting on the dispute describes competing interpretations of the voting provisions. These positions should be distinguished from a final judicial determination of the appointment’s validity.
See more of our coverage in your search results.
Add INDYASTORY on GoogleThe governance issue is therefore procedural as well as personal. A leadership decision needs an appointment process whose authority is clear to the parties expected to implement it.
Shareholder influence and management autonomy serve different purposes
A controlling shareholder has a substantial interest in leadership, strategy and the stewardship of its investment. Professional management needs sufficient authority to execute an agreed strategy and take responsibility for the outcome.
Neither requirement disappears because the other exists.
From a governance perspective, shareholder confidence works best alongside explicit decision-making boundaries. Those boundaries should establish which matters require shareholder approval, which belong to the board and which are delegated to executives.
If those distinctions remain uncertain, disagreements can recur through individual appointments, investment decisions and performance reviews.
This is an analytical concern, rather than evidence that every operating decision across the Tata group has been disrupted.
What Laveesh Bhandari’s argument adds
In his October 27 column, Laveesh Bhandari approaches the dispute through organisational design. He argues that a professional leader requires both strategic freedom and clear accountability, supported by the confidence of Tata Trusts.
His analysis also questions whether dividing authority through a compromise arrangement would provide an effective basis for leadership. These are the author’s governance arguments, rather than announced Tata policy or an independently established assessment of the group’s internal workings.
The useful question for readers is how an arrangement would function in practice: who approves strategy, who allocates capital, who evaluates results and who resolves a disagreement?
Why clear authority matters across the group
A holding company must assess competing demands for capital while overseeing investments with different risks and timelines.
Uncertainty about leadership authority can make that task harder if participants disagree about who can approve a decision or whether an approval will remain accepted.
At the same time, a unified leadership structure does not remove the need for independent scrutiny. Strong governance should allow directors to challenge proposals, request information and record dissent without leaving the organisation unable to act.
The objective is a decision-making process that accommodates disagreement and produces an outcome through recognised procedures.
What to watch next
The most consequential developments will be formal company and Trusts statements, the applicable shareholder processes and any authoritative resolution of the disputed voting provisions.
Readers should distinguish between a board announcement, a shareholder objection and a legally settled outcome. They represent different stages of the dispute.
For Tata Sons, the lasting governance challenge is to establish a leadership mandate that combines valid appointment procedures, shareholder confidence and measurable accountability. Resolving the identity of the chairman addresses only part of that task.